EIS AI Expenditure: How to Track the 400% Deduction in Xero
The tax deduction for AI spend is generous. First you have to show which spend was AI.
In the recent Singapore Budget 2026, the government announced the new EIS AI expenditure deduction. It sits within the Enterprise Innovation Scheme (EIS), which currently exists to give businesses enhanced tax deductions on activities such as R&D and training. For YA 2027 and YA 2028, the scheme will expand to cover adopting AI: businesses can deduct 400% of the first S$50,000 a year they spend on qualifying AI tools and related services, where other ordinary business expense gets 100%.
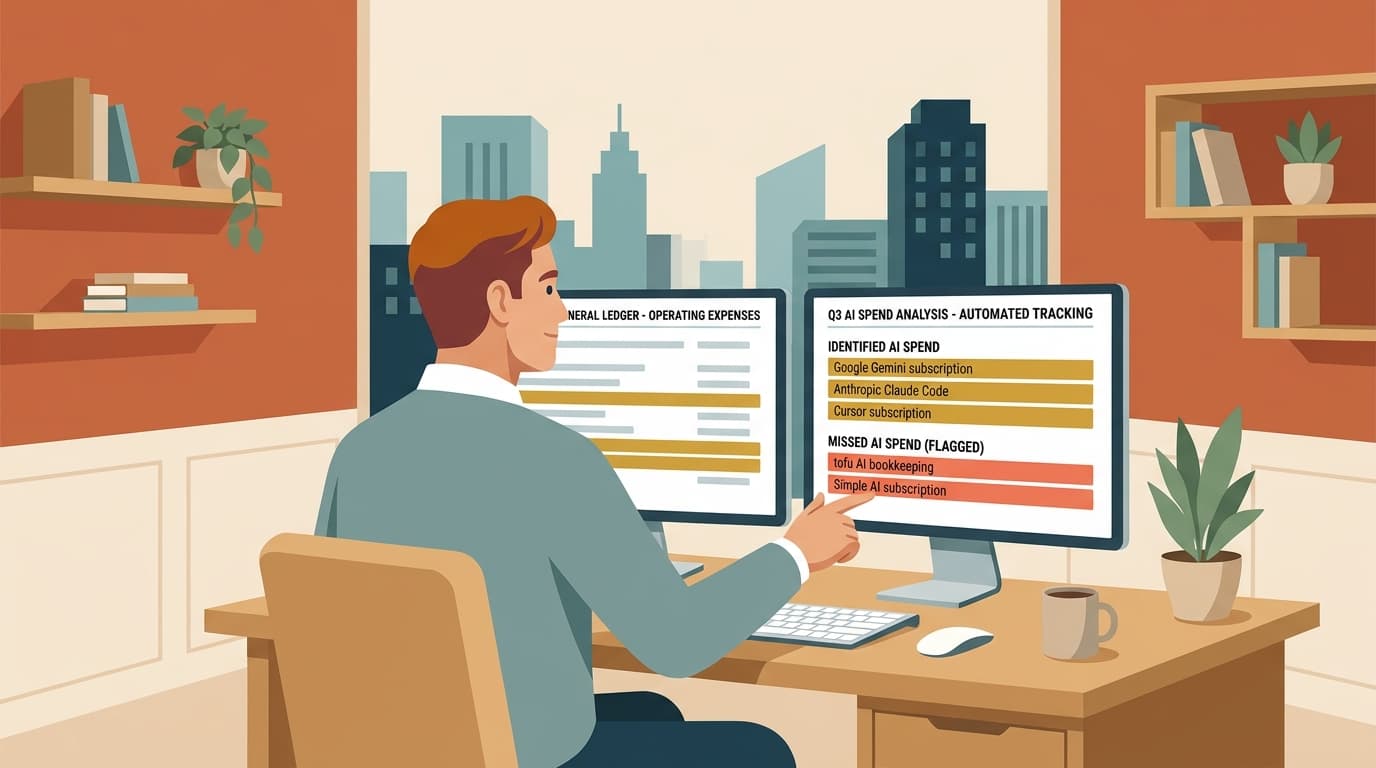
Claiming it is harder than it sounds. Sometime next year, your tax agent's request list arrives with a new line on it: qualifying AI expenditure for the year. You open Software & Subscriptions in Xero. It has hundreds of lines: chat assistant seats on a company card, a CRM that added AI to its top tier, Microsoft, Adobe, and an accounting integration nobody remembers buying. Somewhere else, under Consulting, sits the invoice from the firm that built your forecasting tool.
Which of those count? How much of each? Was any of it grant-funded?
The deduction is generous, but your ledger was never set up to answer the question. If your year ends on 31 December, the first of only two claim years closes in eight weeks. This post covers what the claim needs from your data, how to set up Xero to hold it and what the claim schedule should look like.
What the EIS AI expenditure deduction needs from your books
IRAS published the detail in the EIS e-Tax Guide on 31 August 2026. Your tax agent will apply the rules. These are the ones that shape your data:
- 400% on the first S$50,000, per YA. That's up to S$200,000 of deductions. At the 17% headline rate, the S$150,000 on top of the normal deduction is worth up to S$25,500 a year. An unused cap can't be carried to the other year.
- The years follow your basis period. For a December year-end, spend in 2026 and 2027 counts. For a June year-end, YA 2027 started on 1 July 2025, so the first year has already closed.
- It's defined by what you bought. Annex F covers subscribing to or licensing an AI system, plus services related to developing, deploying, operating or maintaining one, including consultancy, data and training. There's no approved provider list in Annex F, so the test falls on each expense.
- Mixed spend has to be split. Only the AI portion of a mixed subscription qualifies, on evidence or a reasonable basis you can document.
- Some spend comes out. Hardware doesn't count, and neither does anything subsidised by a Government grant. Nor can an amount claimed under certain other sections of the Income Tax Act be claimed again here.
- There's no cash option. Unlike most of the EIS, AI spend can't convert to a cash payout. A loss-making company carries the deduction forward or uses group relief or carry-back, subject to the usual conditions.
- The cap sits at company level. A group with five Singapore companies has five caps and five schedules, not one.
Every one of those is a data requirement. You need each expense by company and basis period, with what it was, why it qualifies, how much of it qualifies and what funded it.
Where native Xero stops
Xero records all of these transactions, but nothing in it was built to answer this question.
AI spend doesn't have an account. It's scattered across software, consulting, training and staff expense claims. The chart of accounts tells you what kind of cost something is, and this claim cuts across those categories.
Tracking is optional. A tracking category is the natural tool, but Xero doesn't require it on any line. Making it mandatory has been on Xero's ideas board since 2012, with 296 votes, and Xero's response is that it "isn't on our roadmap for development." So a line nobody tagged doesn't raise an error. It just isn't in your total.
The slots may be taken. Xero allows two active tracking categories. If you already use Location and Department, an EIS category means giving one up.
A line holds one coding. Xero can code a S$12,000 subscription to one tracking option. Splitting it means two lines, and your apportionment workings still live somewhere else.
The P&L view misses the balance sheet. Tracking reports centre on profit and loss. An annual licence in prepayments, or software capitalised as an asset, sits on the balance sheet, so a tracked P&L can understate it. This matters because capital spend that isn't deductible under section 14 can still get the 400% within the cap, while the excess above the cap gets no base deduction.
There's nowhere to record the reason. Xero has no field for "why this qualifies", "basis of split" or "grant received". That reasoning usually lives in someone's head until the agent asks.
How to set up Xero now
Do this before the next month-end, then deal with the backlog once.
- Add the marker. If a tracking slot is free, create a category such as "EIS AI" with options like Subscription, Service and Mixed. If both slots are in use, create dedicated expense accounts, such as "AI subscriptions" and "AI services". Accounts are harder to miss but they add clutter, and they don't help with balance sheet items.
- Set defaults for AI-only suppliers. A contact can carry default tracking, so a dedicated AI vendor gets tagged on each new bill. Don't do this for mixed suppliers, because it would tag their ordinary spend too.
- Keep the amounts in the right form. Split mixed subscriptions into two lines when the invoice allows it. For GST-registered businesses, the claimable amount excludes GST you can claim as input tax. Foreign currency bills, which most AI subscriptions are, need a Singapore dollar figure you can trace.
- Catch the awkward routes. Check staff expense claims and company cards, where small seats tend to hide. Then check prepayments, and carry the tag onto any journal that releases them.
- Backfill to the start of the basis period. Export Account Transactions for each relevant account and review them line by line. Find and recode can add tracking to existing lines, though Xero limits it to users with the adviser role.
- Review the untagged lines monthly. Scan software, consulting and training for new suppliers. Ten minutes a month beats a day in the next filing season.
Then ask your tax agent the questions the guide leaves to judgement: how to treat an annual subscription that straddles two basis periods, and whether a mixed item's basis will hold. Ask now, while you can still change how you record things.
What an EIS claim schedule looks like
The claim is declared in the Enterprise Innovation Scheme section of the company's income tax return. Businesses must also keep adequate records and provide them to IRAS on request. So the schedule has to work on its own, a year or more later, for someone who wasn't there.
One row per expense, for one company and one basis period. Here's a slice, in Singapore dollars, excluding claimable GST:
| Supplier | What it is | Cost | AI portion | Basis | Grant | Qualifying |
|---|---|---|---|---|---|---|
| Vendor A | Chat assistant seats | 9,600 | 9,600 | AI system | 0 | 9,600 |
| Vendor B | CRM top tier with AI | 12,000 | 4,000 | Tier price difference | 0 | 4,000 |
| Vendor C | Forecasting tool build and staff training | 28,000 | 28,000 | AI business service | 8,000 | 20,000 |
| Vendor D | General management consultancy | 15,000 | 0 | Not AI related | 0 | 0 |
| Vendor E | Server for local models | 6,000 | 0 | Hardware excluded | 0 | 0 |
| Total | 33,600 |
That's S$33,600 against the S$50,000 cap, so S$134,400 of total deductions at 400%. The rejected rows are as useful as the others, since they show that someone reviewed the spend and made a decision.
Behind each row, the schedule should link to the Xero transaction and invoice, and show the invoice date, service period, payment date and account. Add a column for whether the item falls under section 14, and a running total against the cap. Then keep a tie-out: the tagged total in the schedule agrees with Xero, and anything excluded is listed with a reason.
Next year, the same layout runs for the second basis period, with the same suppliers already classified. Only the new ones need a decision.
What going without it looks like
The small company that finds out in October. The tax agent's question arrives in the run-up to the 30 November deadline. The bookkeeper spends two days reading card statements and invoices from 18 months ago, and the small seats don't get found, because nobody remembers them.
The group with one shared subscription. The parent pays for AI seats used across four companies. Each company has its own cap, so the cost and the recharge need to land in the right file with the same tag. With separate Xero organisations, that's four exports and four sets of workings.
The firm with 40 clients. Every client asks the same question, each with a different chart of accounts, and half have used their tracking slots already. A checklist helps, but the review is still manual for each client, every year.
The workarounds, ranked
- Sort it out at filing time. The default. It works if your spend is three obvious invoices. Otherwise it costs the most hours and misses the most money.
- A running spreadsheet. Someone logs each AI purchase as it happens. It's flexible, and it holds the reasoning. It also depends on one person noticing every purchase, with nothing checking it against Xero.
- Tracking plus a monthly export. Tag lines in Xero, export them, and add the split and reason columns. This is the right starting point for most small companies. Balance sheet items and untagged lines still need checking by hand.
- An add-on or tax software. Tax computation tools handle the computation well. Check whether yours identifies the AI spend inside Xero, or only expects you to arrive with the number.
- A generated schedule from the Xero API. Pull every line from the relevant accounts and balance sheet, apply your supplier mapping, flag anything new or untagged, and write the schedule. It's repeatable and handles several companies. It's also a real build, and it's overkill for a single company with three AI invoices.
Where Cheetah fits
The claim schedule is a recurring report with a judgement layer, which is the kind of thing we build at Cheetah. We encode your rules once: which accounts and suppliers to scan, how mixed items split, what's been grant-funded and which basis periods apply. Each month, the report pulls the lines from Xero, including the balance sheet accounts, and lists anything new or untagged for someone to decide on. AI helps us build reports, but it doesn't produce the numbers, so each figure traces back to a Xero transaction.
It arrives in Google Sheets with plain formulas and an Excel download, one tab per company, ready to hand to your tax agent. We don't decide what qualifies. Your agent still does that, but they get to do it from a complete list.
If you're spending on AI across several Xero files and nobody's keeping count, it might be worth a conversation.
The short version
The EIS AI expenditure deduction gives 400% on up to S$50,000 for each of YA 2027 and YA 2028, with no cash option and no combining across years. Claiming it means separating AI spend from ordinary software and consultancy, splitting mixed items and netting off grants, company by company. Xero can hold the data if you set up a tracking category or dedicated accounts now, but it won't enforce the tagging or hold your reasoning, so build the claim schedule alongside it and review it monthly. For the wider options, see Xero Custom Reports: 4 Ways to Build Them in 2026.
Frequently asked questions
- What is the EIS AI expenditure deduction?
- Budget 2026 added adoption of AI to Singapore's Enterprise Innovation Scheme. Businesses can deduct 400% of the first S$50,000 of qualifying AI expenditure for each of YA 2027 and YA 2028. The cap can't be combined across years, and this category can't be converted into a cash payout.
- Which financial years count for YA 2027 and YA 2028?
- A Year of Assessment taxes the financial year ending in the year before it. For a 31 December year-end, YA 2027 covers spend in 2026 and YA 2028 covers spend in 2027. For a 30 June year-end, YA 2027 covers 1 July 2025 to 30 June 2026.
- What counts as qualifying AI expenditure?
- Subscribing to or licensing an AI system, and subscribing to, acquiring or licensing a qualifying AI business service, such as development, consultancy, data, compliance or training services related to an AI system. Servers and other hardware are excluded, as is anything subsidised by a Government grant.
- Does the AI provider have to be on an approved list?
- IRAS's e-Tax Guide defines qualifying AI expenditure by what was bought and sets no list of approved providers or qualifying partners for this activity. Check the guide's current edition with your tax agent, because IRAS can vary its position.
- What if a software subscription is only partly AI?
- Only the AI portion qualifies. If you can't get evidence of the split despite reasonable efforts, apportion on a reasonable basis and keep the workings for IRAS. One basis IRAS gives is the price difference between the same package with and without its AI capabilities.
- What happens if my company makes a loss?
- Enhanced deductions that can't be used become unutilised trade losses or allowances. Subject to the usual conditions, they can be carried forward, transferred under group relief or carried back one YA. There is no cash payout option for AI expenditure.
A finance professional turned product builder, Jarvin has built hundreds of reports by hand and knows what financial and operational reporting demands: customisability, auditability, scalability, and security. Having automated that work reliably, he's now helping advisory firms and finance teams do the same.
